1
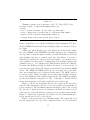
Cantrell, Steve, Michael T. Maloney, and Mark Mitchell. “On Estimating
the Variance of Abnormal Stock Market Performance,” working paper,
1989, Clemson University.
Chandra, Ramesh, and Bala V. Balachandran. “A Synthesis of Alternative Testing Procedures for Event Studies,” Contemporary Accounting
Research, 1990, 6(2), 611–640.
Chandra, Ramesh, Shane Moriarity, and G. Lee Willinger. “A Reexamination of the Power of Alternative Return-Generating Models and the
Effect of Accounting for Cross-Sectional Dependencies in Event Studies,” Journal of Accounting Research, 1990, 28(2), 398–408.
Chen, Haiyang, Michael Y. Hu, and Joseph C.P. Shieh. “The Wealth Effect
of International Joint Ventures: The Case of U.S. Investment in China,”
Financial Management, 1991, 20(4), 31–41.
Corhay, A. and A. Tourani Rad. “Conditional Heteroscedasticity Adjusted
Market Model and an Event Study,” Quarterly Review of Economics
and Finance, 1996, 36(4), 529–538.
Collins, Daniel W. and Warren T. Dent. “A Comparison of Alternative
Methodologies used in Capital Market Research,” Journal of Accounting
Research, 1984, 22(1), 48–84.
Corrado, Charles J. “A Nonparametric Test for Abnormal Security-Price
Performance in Event Studies,” Journal of Financial Economics, 1989,
23(2), 385–396.
Corrado, Charles J., and Terry L. Zivney, “The Specification and Power
of the Sign Test in Event Study Hypothesis Tests Using Daily Stock
Returns,” Journal of Financial and Quantitative Analysis, 1992, 27(3),
465–478.
Cowan, Arnold R. “Nonparametric Event Study Tests,” Review of Quantitative Finance and Accounting, 1992, 2(4), 343–358.
Cowan, Arnold R. “Tests for Cumulative Abnormal Returns over Long Periods: Simulation Evidence,” International Review of Financial Analysis,
1993, 2(1), 51–68.
Cowan, Arnold R., Nandkumar Nayar, and Ajai K. Singh. “Stock Returns
Before and After Calls of Convertible Bonds,” Journal of Financial and
Quantitative Analysis, 1990, 25(4), 549–554.
164