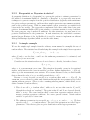
1
1.1.2
Computational basis of admb-re
• Hyper-parameters (variance components, etc.) estimated by maximum likelihood.
• Marginal likelihood evaluated by the Laplace approximation, (adaptive) importance
sampling or Gauss-Hermite integration.
• Exact derivatives calculated using Automatic Differentiation.
• Sampling from the Bayesian posterior using mcmc (Metropolis-Hastings algorithm).
• Most of the features of ordinary admb (matrix arithmetic and standard errors, etc.)
are available.
• Sparse matrix libraries, useful for Markov random fields and crossed random effects,
are available.
1.1.3
The strengths of admb-re
• Flexibility: You can fit a large variety of models within a single framework.
• Convenience: Computational details are transparent. Your only responsibility is to
formulate the log-likelihood.
• Computational efficiency: admb-re is up to 50 times faster than Winbugs.
• Robustness: With exact derivatives, you can fit highly nonlinear models.
• Convergence diagnostic: The gradient of the likelihood function provides a clear convergence diagnostic.
1.1.4
Program interface
• Model formulation: You fill in a C++-based template using your favorite text editor.
• Compilation: You turn your model into an executable program using a C++ compiler
(which you need to install separately).
• Platforms: Windows, Linux and Mac.
1.1.5
How to obtain admb-re
admb-re is a module for admb. Both can be obtained from admb-project.org.
1-3