1
Appendix
Abnormal Returns
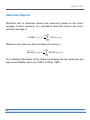
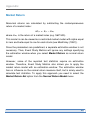
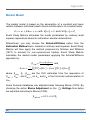
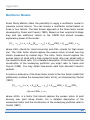
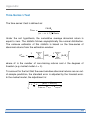
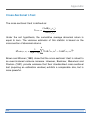
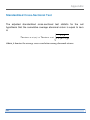
Statistical test of abnormal returns are commonly based on the crossaverage of each measure. For cumulative abnormal returns the crosssectional average is:
CAAR τH , τS
a
1
T R:BC LH , LS
N
bWH
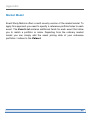
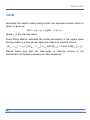
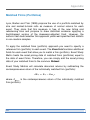
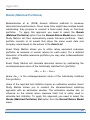
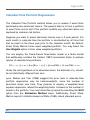
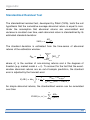
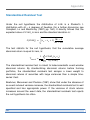
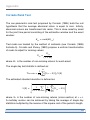
Whereas, the mean buy-and hold abnormal return is:
cccccccc
YZ:B LH , LS
a
1
T YZ:BC LH , LS
N
bWH
For a detailed discussion of the difference between the two measures you
may consult Barber and Lyon (1997) or Ritter (1991).
62