1
Appendix
Market Return
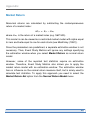
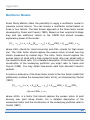
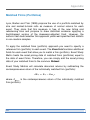
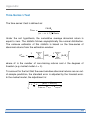
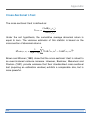
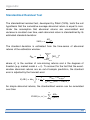
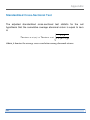
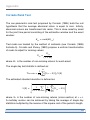
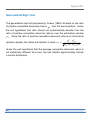
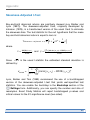
Abnormal returns are calculated by subtracting the contemporaneous
return of a market index:
:BC,E
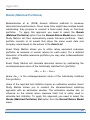
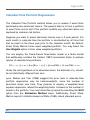
BC,E − Bq,E
where Bq,E is the return of a market index (e.g. S&P 500).
This model is can be viewed as a restricted market model with alpha equal
to zero and beta equal to one for each stock (see MacKinlay (1997)).
Since the parameters are predefined, a separate estimation window is not
necessary. Thus, Event Study Metrics will ignore any settings specifying
the estimation window when you select Market Return as normal return
model.
However, some of the reported test statistics require an estimation
window. Therefore, Event Study Metrics also allows you to apply the
market return model with an estimation window. The estimation window
has no influence on the normal return measure itself, but is solely used to
calculate test statistics. To apply this approach you need to select the
Market Return Est option from the Normal Return Model menu.
65